Compliance you can check, not just claim.
Free tools and guides for lenders.
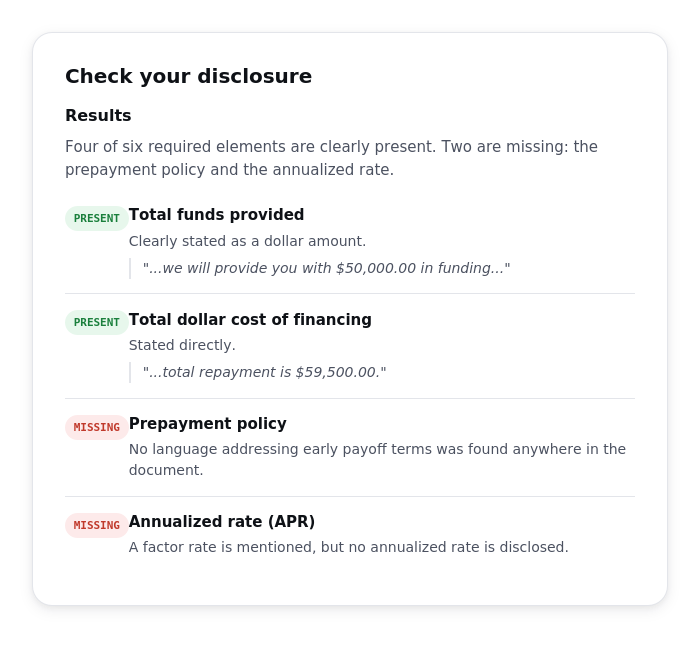
Know what's missing before a regulator does.
Upload a disclosure. Every gap, quoted from your own document.
Decline notices that hold up.
Adverse action, generated from your actual decision.
Q3 2026, in five numbers.
Fed and BofA data on where US credit access stands right now.
Embed compliance into your stack.
One endpoint. Check or generate, from your own app.
{ "state": "CA" }
// 200 OK
{ "missing": ["prepayment"] }
Ask someone who's run the book.
Product, risk and growth, operator to operator.
Smaller lenders pay disproportionately for compliance. Community banks spend 11 to 15.5 percent of payroll on compliance tasks, nearly double what larger institutions spend, mostly because they lack a dedicated compliance team, not because the rules are unknowable.
Regulators are not going easy on this.
In January 2025, the New York Attorney General won a $1.065 billion judgment against Yellowstone Capital, canceled roughly $534 million in debt for more than 18,000 small businesses, and permanently banned the company from the industry.*
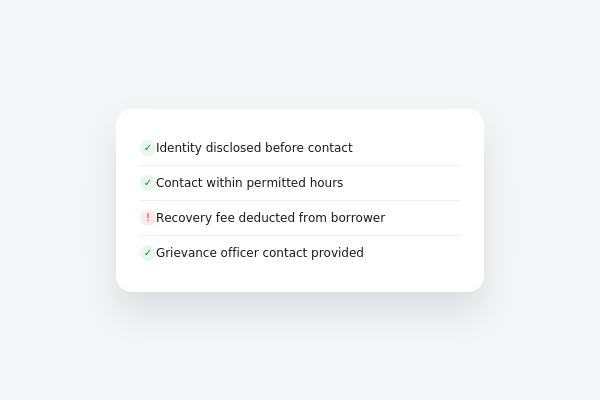
India's RBI has moved just as aggressively: it cancelled the registration of over 200 NBFCs in under six months through early 2026, including a single sweep of 150 in April, and fined established names like Manappuram Finance and IIFL Finance for compliance lapses many would consider routine paperwork.‡
Prefer email? Get notified only when a new guide goes up, no other noise.